
Principles of Accounting — The System of Accounting Standards: K-IFRS, K-GAAP and the SME Standards
The final chapter of principles of accounting looks at where the rules used so far come from. The same transaction can produce different numbers depending on the standard applied. When reading or preparing financial statements, the first thing to check is which standards this company uses.
1. Who sets the standards, and their force
International standards are issued by the International Accounting Standards Board (IASB) under the IFRS Foundation. In Korea, under Article 5 of the Act on External Audit of Stock Companies, the Financial Services Commission sets accounting standards and delegates the work to the Korea Accounting Standards Board (KASB). Standards take effect when the KASB’s Accounting Standards Committee resolves them and the Financial Services Commission approves them.
2. Three frameworks and who applies them
| Standard | Applies to | Features |
|---|---|---|
| Korean IFRS (K-IFRS) | Listed companies, financial institutions, etc. (mandatory); other companies may opt in | Almost identical to IFRS; consolidated statements are the primary statements |
| General Accounting Standards (K-GAAP) | Externally audited companies not using K-IFRS | Rules-based, tailored to Korean practice; centred on separate statements |
| Accounting Standards for SMEs | Stock companies not subject to external audit | Based on the Commercial Act Enforcement Decree; simplified treatments |
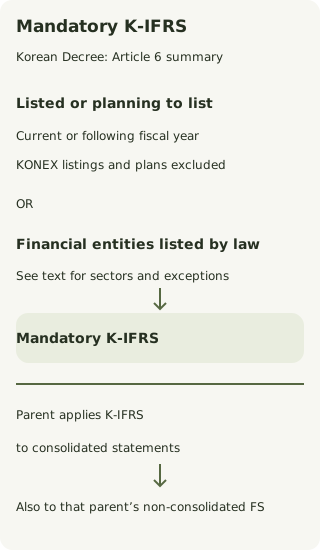
Mandatory K-IFRS application is assessed separately from external-audit status. Article 6(1) lists stock-listed companies and companies planning to list in the current or following fiscal year (excluding KONEX in both cases), financial holding companies (excluding statutory conversion candidates), banks, investment traders and brokers, collective investment business entities, trust business entities and merchant banks, insurers, and credit-card business entities. Under Article 6(2), a parent applying K-IFRS to consolidated statements must also apply it to its non-consolidated statements. Asset size or external-audit status alone therefore does not determine mandatory K-IFRS application. Official scope
Korea has required listed companies to apply K-IFRS since 2011. K-IFRS numbers IAS-series standards 10xx and IFRS-series standards 11xx. For example, IAS 16 (property, plant and equipment) is K-IFRS 1016, IFRS 15 (revenue) is K-IFRS 1115 and IFRS 18 (presentation and disclosure) is K-IFRS 1118.
A. Principles-based and rules-based
K-IFRS is a principles-based standard that sets principles and leaves judgement to the entity, in exchange requiring detailed disclosure of the basis for those judgements in the notes. K-GAAP has relatively specific rules that make it easier to apply but leave less room to interpret new kinds of transactions.
3. Examples where the numbers differ by standard
A. Goodwill
A company acquires another company and pays ₩10 million more than the fair value of its net assets. That ₩10 million is goodwill.
| Year | K-IFRS | K-GAAP (useful life of 10 years assumed) |
|---|---|---|
| Expense in year 1 | 0 (no indication of impairment; tested annually) | 100 (straight-line amortization) |
| Carrying amount at end of year 5 | 1,000 | 500 |
| If impaired | Impairment loss recognized; no reversal | Impairment loss recognized |
For the same acquisition, the cumulative profit difference over five years is ₩5 million. When comparing the profits of acquisitive companies, this difference must be adjusted for.
B. The centre of consolidation
A parent using K-IFRS presents consolidated financial statements as its primary statements. K-GAAP also requires consolidation, but Korean disclosure practice has centred on separate statements. For a group with many subsidiaries, separate and consolidated debt ratios can differ widely.
C. Other differences
Differences also arise in the criteria for recognizing development costs as assets, the scope for revaluing property, plant and equipment, the classification of financial instruments and lease accounting (K-IFRS recognizes most leases as right-of-use assets and lease liabilities). Each item is covered under K-IFRS in Intermediate Accounting.
4. Choosing and switching standards
A company using K-GAAP that prepares to list switches to K-IFRS. It restates its statement of financial position at the transition date under the new standards and must present comparative figures under them too (K-IFRS 1101 First-time Adoption). Exemptions from retrospective application can be chosen for some items.
Check your understanding
Company H (K-GAAP, goodwill useful life five years) and company I (K-IFRS) each acquire another company on the same day and recognize goodwill of ₩6 million. What are each company’s total goodwill-related expenses over the three years after acquisition and the goodwill carrying amount at the end of year 3? What happens if I’s impairment test in year 3 shows that the recoverable amount of the cash-generating unit including goodwill is ₩1.5 million below its carrying amount?
H amortizes (₩10,000) each year, so total expense over three years is ₩3.6 million and the carrying amount at the end of year 3 is ₩2.4 million. I does not amortize, so without impairment the expense is 0 and the carrying amount ₩6 million. If an impairment of ₩1.5 million is identified in year 3, I first reduces goodwill by ₩1.5 million, for total expense of ₩1.5 million and a carrying amount of ₩4.5 million. A goodwill impairment loss is not reversed even if the recoverable amount later recovers.
References
- Act on External Audit of Stock Companies, Article 5 (accounting standards) — National Law Information Center
- Korea Accounting Standards Board, accounting standards
- Korea Accounting Standards Board, K-IFRS 1101 First-time Adoption of Korean International Financial Reporting Standards; K-GAAP chapter 12 Business Combinations
Oiyo
Editorial DeskThe OIYO editorial desk researches money, law, lifestyle, and self-understanding topics against primary sources and public statistics. Every piece carries source notes and is reviewed on a regular cycle for accuracy and usefulness.