
Principles of Accounting — Property, Plant and Equipment: Cost, Depreciation and Disposal
Property, plant and equipment are assets used over several years, such as buildings, machinery and vehicles. Accounting asks two questions: at what amount to record them initially, and at what pace to turn that cost into expense. The standard is K-IFRS 1016 Property, Plant and Equipment (IAS 16). The revaluation model and impairment are covered in Intermediate Accounting chapter 3 and chapter 5.
1. What goes into cost and what does not
Cost comprises the costs directly attributable to bringing the asset to the location and condition necessary for it to be capable of operating in the manner intended by management.
| Item | Amount | Treatment |
|---|---|---|
| Purchase price (net of trade discounts) | 900 | Cost |
| Delivery and installation | 60 | Cost |
| Testing (before deducting proceeds from samples) | 20 | Cost |
| Professional fees related to acquisition | 20 | Cost |
| Staff training | 15 | Expense |
| Initial operating losses | 30 | Expense |
Cost is ₩10 million. Since the 2022 amendment to the standard, proceeds from selling samples produced during testing are not deducted from cost but recognized as revenue. For equipment with a dismantling and restoration obligation, the present value of the estimated cost is also added to cost, with the same amount recognized as a restoration provision.
2. Depreciation is an allocation of cost
Depreciation is not a valuation tracking the asset’s market value. It is the systematic allocation of the depreciable amount (cost − residual value) over the useful life. The method chosen should reflect the pattern in which economic benefits are consumed, and residual value, useful life and method are reviewed at least at each financial year-end.
A. Comparing three methods
A machine costing ₩10 million, with a residual value of ₩1 million and a useful life of five years, is acquired on 1 January.
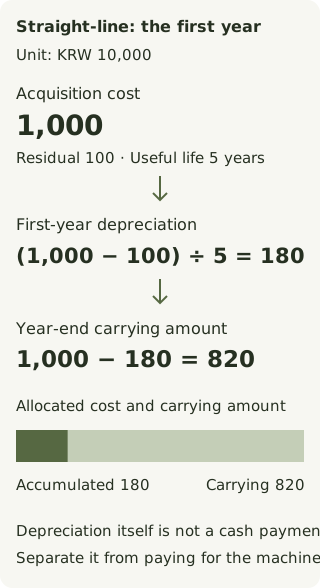
| Year | Straight-line | Sum-of-the-years'-digits | Diminishing balance (40%) |
|---|---|---|---|
| 1 | 180 | 300 (900 × 5/15) | 400 (1,000 × 40%) |
| 2 | 180 | 240 (900 × 4/15) | 240 (600 × 40%) |
| 3 | 180 | 180 (900 × 3/15) | 144 (360 × 40%) |
| 4 | 180 | 120 (900 × 2/15) | 86.4 (216 × 40%) |
| 5 | 180 | 60 (900 × 1/15) | 29.6 (down to residual value) |
| Total | 900 | 900 | 900 |
Whatever the method, the five-year total is ₩9 million. Accelerated depreciation, heavy in the early years, reduces first-year profit and increases later profit. For an asset whose benefits are used up early because technology changes fast, accelerated depreciation is closer to economic substance; for a building used evenly each year, the straight-line method is.
B. Component depreciation
Where significant parts of an item have different useful lives, such as an aircraft’s engines and airframe, each part is depreciated separately. Land is treated as having an unlimited life and is not depreciated. When land and a building are bought together, the price is split by relative fair values and only the building portion is depreciated.
3. Subsequent costs: asset or expense?
Expenditure after acquisition is added to the carrying amount if it increases future economic benefits and its cost can be measured reliably. If replacing an engine extends the useful life, the cost of the new engine is capitalized and the carrying amount of the replaced engine is derecognized. Routine repairs and maintenance are expenses of the period incurred. The former is often called capital expenditure and the latter revenue expenditure.
4. Disposal and derecognition
On disposal, the asset is depreciated up to the disposal date, and the difference between the proceeds and the carrying amount is recognized as a gain or loss on disposal.
The straight-line machine above is sold on 1 July of year 3 for ₩4.5 million. Accumulated depreciation to the disposal date is and the carrying amount is (₩10,000). The loss on disposal is , i.e. ₩1 million.
| Debit | Amount | Credit | Amount |
|---|---|---|---|
| Depreciation expense (six months of year 3) | 90 | Accumulated depreciation | 90 |
| Cash | 450 | Machinery | 1,000 |
| Accumulated depreciation | 450 | ||
| Loss on disposal of PP&E | 100 |
Check your understanding
Company D bought a vehicle for ₩24 million on 1 April 20X1. The residual value is ₩4 million, the useful life four years, and it is depreciated by the sum-of-the-years’-digits method (monthly proration). What is depreciation for 20X1 and 20X2? If the vehicle is sold for ₩12 million at the end of 20X2, what is the gain or loss?
The depreciable amount is ₩20 million and the sum of the years is . Depreciation for the first year of use (April 20X1–March 20X2) is and for the second year (₩10,000). 20X1 carries nine months: . 20X2 carries the remaining three months of the first year, 200, plus nine months of the second year, 450, for a total of 650. The carrying amount at the end of 20X2 is , so selling for ₩12 million gives a gain of ₩500,000.
References
- Korea Accounting Standards Board, K-IFRS 1016 Property, Plant and Equipment (including the 2022 amendment on proceeds before intended use)
- Korea Accounting Standards Board, K-IFRS 1037 Provisions, Contingent Liabilities and Contingent Assets (restoration provisions)
- Jerry Weygandt, Paul Kimmel and Donald Kieso, Financial Accounting with International Financial Reporting Standards, ch. 9
Oiyo
Editorial DeskThe OIYO editorial desk researches money, law, lifestyle, and self-understanding topics against primary sources and public statistics. Every piece carries source notes and is reviewed on a regular cycle for accuracy and usefulness.