
Principles of Accounting — The Income Statement: Classifying Expenses and When to Recognize Revenue
The income statement shows the performance of one period. K-IFRS 1001 (IAS 1) allows profit and other comprehensive income to be shown in a single statement (the statement of comprehensive income) or profit to be shown in a separate income statement. This chapter covers the structure down to profit: how expenses are grouped and when revenue is recognized. Other comprehensive income was covered in chapter 4.
1. Classifying expenses: by function and by nature
Expenses are presented using one of two classifications.
- By function (cost of sales method): expenses are grouped by the activity they served, such as cost of sales, distribution costs and administrative expenses. Gross profit becomes visible.
- By nature: expenses are grouped by their nature, such as raw materials used, employee benefits and depreciation. No judgement is needed to allocate them to activities, so it is simpler to prepare.
An entity classifying by function must additionally disclose information by nature, such as depreciation and employee benefits, in the notes, because information by nature is needed to forecast future cash flows.
2. The same company in two formats
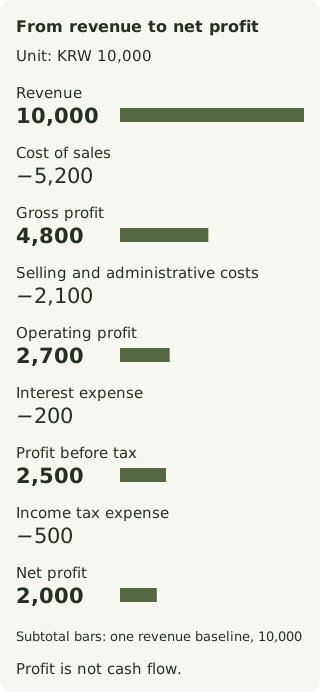
A manufacturer’s figures for the year are as follows (unit: ₩10,000). Sales 10,000. Raw materials used 3,000; employee benefits 2,500 (production 1,500, selling 600, administration 400); depreciation 1,000 (production 700, selling 100, administration 200); other selling and administrative expenses 800. There is no difference between opening and closing finished goods. Interest expense 200; income tax expense 500.
| Item | Amount | Working |
|---|---|---|
| Revenue | 10,000 | |
| Cost of sales | (5,200) | Raw materials 3,000 + production salaries 1,500 + production depreciation 700 |
| Gross profit | 4,800 | |
| Selling and administrative expenses | (2,100) | Salaries 1,000 + depreciation 300 + other 800 |
| Operating profit | 2,700 | |
| Finance costs | (200) | |
| Profit before tax | 2,500 | |
| Income tax expense | (500) | |
| Profit for the year | 2,000 |
Presented by nature, deducting raw materials used 3,000, employee benefits 2,500, depreciation 1,000 and other 800 in turn from revenue of 10,000 gives the same operating profit of 2,700. The later steps are identical. Operating profit and profit are the same in both formats; only the intermediate steps look different.
A. Operating profit in Korea
IFRS had no definition of operating profit, but when Korea adopted K-IFRS it added paragraphs requiring operating profit to be shown on the face of the income statement or in the notes. Operating profit is revenue less cost of sales and selling and administrative expenses. Gains and losses on disposal of property, plant and equipment or foreign exchange differences go below operating profit as other income and other expenses.
B. Presentation changing from 2027
IFRS 18 Presentation and Disclosure in Financial Statements, issued by the IASB in 2024, is being adopted in Korea as K-IFRS 1118, to apply to annual periods beginning on or after 1 January 2027. It divides income and expenses into operating, investing and financing categories, requires an operating profit subtotal from all entities, and requires management-defined performance measures (MPMs) to be reconciled in the notes. The format in this chapter follows the current K-IFRS 1001.
3. When is revenue recognized?
Revenue is recognized when a performance obligation is satisfied by transferring control of the promised goods or services to the customer (K-IFRS 1115, IFRS 15). When cash is received is not the test.
| Transaction | When recognized | Basis |
|---|---|---|
| Sale of goods | When the customer takes delivery and controls the goods | Satisfied at a point in time |
| 12-month maintenance contract | Spread over the 12 months | Satisfied over time |
| Sale of prepaid gift vouchers | When the voucher is redeemed | Cash received is a contract liability |
| Three-year construction contract | By measure of progress | Customer controls the work in progress |
For example, if a one-year maintenance contract of ₩12 million is received on 1 December, revenue in the December year-end income statement is ₩1 million and the remaining ₩11 million is a contract liability. The full five-step model is calculated in Intermediate Accounting chapter 10.
4. Points to watch when interpreting
Check your understanding
Suppose that of the ₩10 million of depreciation in section 2, the ₩7 million attributed to production equipment actually related to the administration building. How do gross profit, operating profit and profit change in the income statement by function? What happens to the income statement by nature?
₩7 million moves from cost of sales to administrative expenses. Cost of sales becomes ₩45 million and gross profit rises by ₩7 million to ₩55 million. Selling and administrative expenses rise to ₩28 million, so operating profit stays at ₩27 million and profit at ₩20 million. The income statement by nature shows depreciation of ₩10 million on one line, so nothing changes. Because allocating expenses to functions can move gross profit substantially, do not judge cost competitiveness from the gross margin alone.
References
- Korea Accounting Standards Board, K-IFRS 1001 Presentation of Financial Statements (including the Korean paragraphs on operating profit)
- Korea Accounting Standards Board, K-IFRS 1115 Revenue from Contracts with Customers
- IASB, IFRS 18 Presentation and Disclosure in Financial Statements (2024)
Oiyo
Editorial DeskThe OIYO editorial desk researches money, law, lifestyle, and self-understanding topics against primary sources and public statistics. Every piece carries source notes and is reviewed on a regular cycle for accuracy and usefulness.