Financial Statement Analysis — Working Capital and Turnover: The Cash Conversion Cycle
The trend analysis of chapter 1 showed FA’s receivables and inventories growing faster than revenue. This chapter checks that signal with turnover and days, and calculates how much cash is tied up in operations (unit: ₩100 million; 365 days a year).
1. Working capital
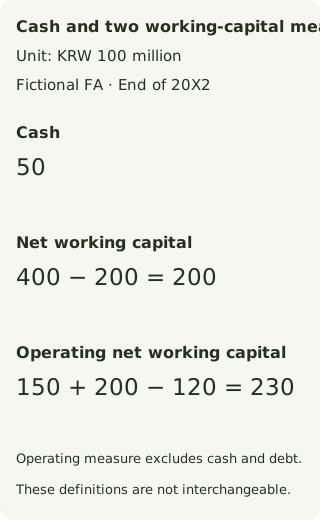
Net working capital conventionally means current assets minus current liabilities: FA’s year-end 20X2 figure is 400−200=200 in units of ₩100 million, as used in chapter 7’s Altman measure. This chapter instead examines operating working capital, excluding cash and interest-bearing borrowings. With no other operating current items in this example, it equals receivables plus inventory minus trade payables. These measures serve different purposes. Below, the shorter term ‘working capital’ refers to this operating scope.
FA’s rose by ₩5 billion, from at the end of 20X1 to at the end of 20X2. That ₩5 billion is money earned as profit but tied up in operations instead of coming in as cash. Operating working capital grew about 28%, faster than the 20% growth in revenue.
2. Turnover and days
| Item | Turnover formula | Turnover | Days (365 ÷ turnover) |
|---|---|---|---|
| Receivables | Revenue 1,200 ÷ average receivables 135 | 8.89 times | 41.1 days (DSO) |
| Inventories | Cost of sales 840 ÷ average inventory 180 | 4.67 times | 78.2 days (DIO) |
| Payables | Cost of sales 840 ÷ average payables 110 | 7.64 times | 47.8 days (DPO) |
Payables turnover should strictly be calculated on purchases; without purchases data, cost of sales is used instead. Purchases can be estimated as cost of sales + closing inventory − opening inventory (₩88 billion for FA, giving 45.6 days).
3. The cash conversion cycle
There are no opening balances for 20X1, so comparing on year-end balances gives DSO of days, DIO of days and DPO of days. On year-end balances for 20X2, DSO is 45.6 days, DIO 86.9 days and DPO 52.1 days. On a like-for-like basis, both receivables days and inventory days have lengthened.
4. Turning days into money
Each extra day ties up that much more cash.
Cutting inventory days from 86.9 to 75 releases one day of cost of sales, about ₩230 million, × 11.9 days ≈ ₩2.74 billion. Together the two recover most of the ₩5 billion increase in net working capital. Managing working capital is a way to generate cash without new financing.
Check your understanding
FD’s annual revenue is ₩73 billion and cost of sales ₩54.75 billion. Average receivables are ₩10 billion, average inventory ₩9 billion and average payables ₩6 billion. What are DSO, DIO, DPO and the cash conversion cycle? If negotiation with suppliers lengthens DPO by 10 days, how much does cash increase?
One day of revenue is ₩200 million and one day of cost of sales ₩150 million. DSO is days, DIO days and DPO days. The cash conversion cycle is days. Lengthening DPO by 10 days raises payables by , i.e. ₩1.5 billion, and that much cash stays in the company.
References
- Krishna Palepu, Paul Healy and Erik Peek, Business Analysis and Valuation: IFRS Edition, ch. 5
- Richard Brealey, Stewart Myers and Franklin Allen, Principles of Corporate Finance, ch. 30
- Korea Accounting Standards Board, K-IFRS 1007 Statement of Cash Flows (disclosure of supplier finance arrangements)
Oiyo
Editorial DeskThe OIYO editorial desk researches money, law, lifestyle, and self-understanding topics against primary sources and public statistics. Every piece carries source notes and is reviewed on a regular cycle for accuracy and usefulness.